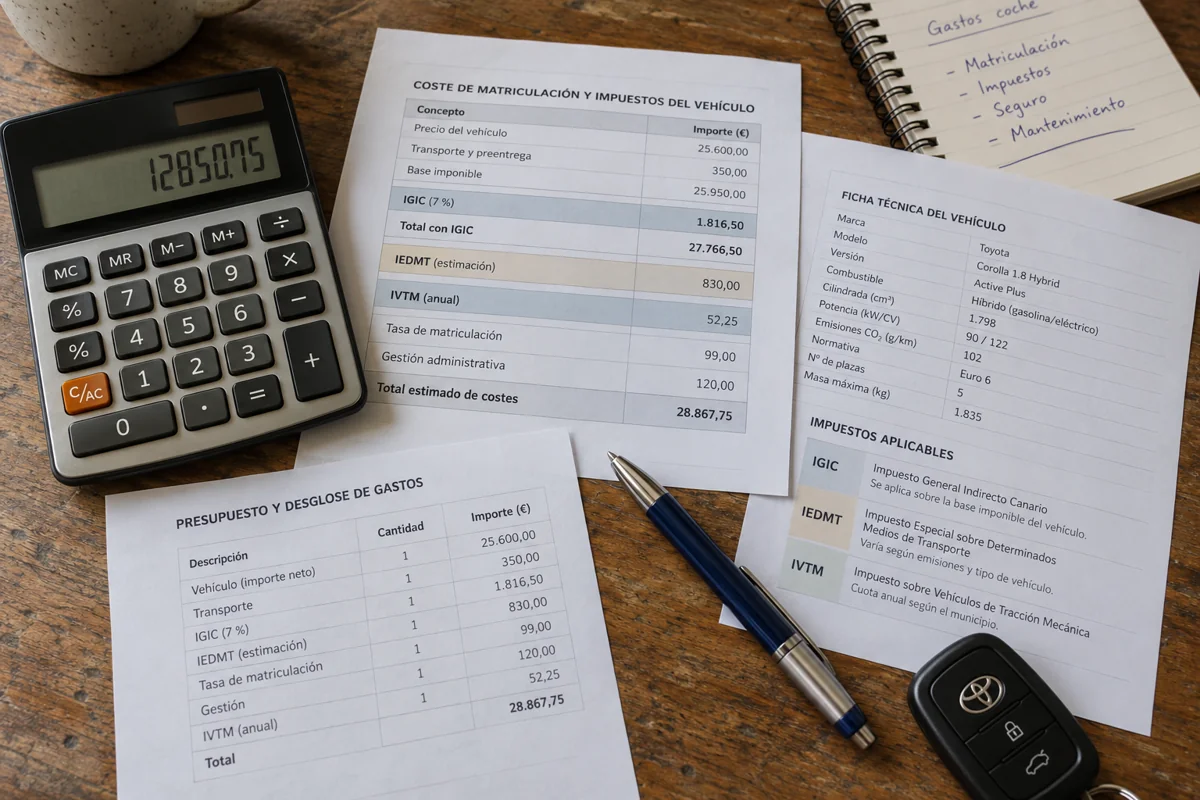
What is the total cost?
There is no single total for every car. Budget for our service fee, third-party charges and the vehicle’s applicable taxes separately. Our fee starts from €249, with IGIC included on that fee. This does not include the vehicle’s IGIC, DGT fee, ITV, technical documents or plates.
IGIC: the Canarian entry tax
A vehicle entering the Canary Islands permanently may be subject to import IGIC even when it comes from mainland Spain or another EU country. The vehicle category, applicable relief and valuation determine the amount. Do not assume the standard general IGIC rate applies to every car or that the purchase invoice is always the final taxable base.
IEDMT: registration tax
For ordinary passenger cars, the Canarian CO₂ bands below apply unless an exemption or different classification changes the result. Official emissions evidence matters; missing required evidence can put a vehicle in the highest band.
| Official CO₂ emissions | Canarian rate |
|---|---|
| Up to and including 120 g/km | 0% |
| Above 120 and below 160 g/km | 3.75% |
| 160 to below 200 g/km | 8.75% |
| 200 g/km or more | 13.75% |
These are not IGIC rates. For a used vehicle, the IEDMT base is determined under the statutory valuation rules, including applicable adjustments; it is not simply whichever price you paid.
IVTM: annual municipal road tax
IVTM is paid to the municipality associated with the vehicle’s tax address. The charge depends on the municipal ordinance and vehicle characteristics, such as fiscal horsepower. It is separate from the one-off registration tax. Payment or exemption evidence is needed for registration.
External charges to budget for
- DGT application fee and number plates.
- ITV inspection, vehicle transport and any repeat inspection.
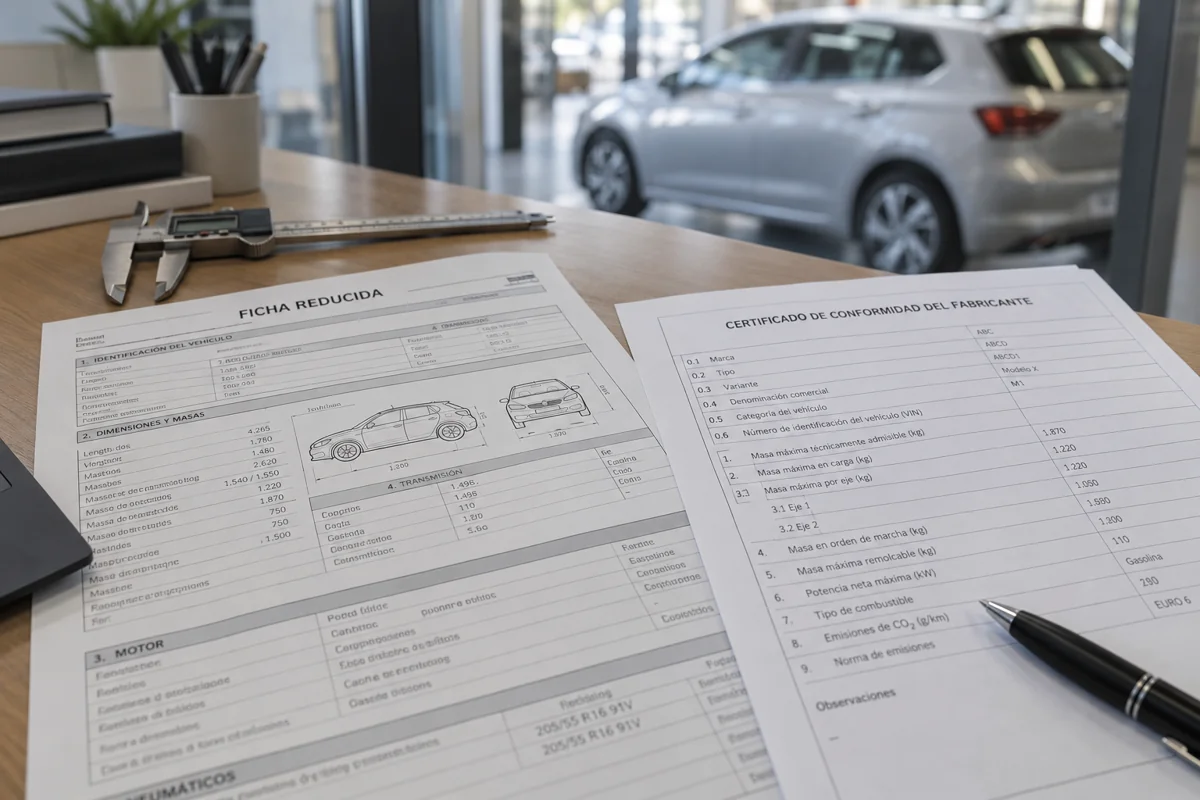
- COC, ficha reducida or additional homologation work where needed.
- Customs-agent charges, translations or other required documentation.
- Repairs or adaptations required to pass inspection.
We identify the applicable items before confirming a quote; not every car requires all of them.
How the arithmetic works
Calculation illustration only: if the confirmed IEDMT taxable base were €20,000 and the applicable rate 3.75%, that tax would be €750. At 8.75%, the same base would produce €1,750. This calculation covers IEDMT only. IGIC, IVTM and fees must be assessed separately.
Can a residence transfer reduce the tax?
Potentially. IGIC and IEDMT have separate relief rules and evidence requirements. Qualifying for one does not automatically qualify you for the other. Obtain the review before importing or allowing deadlines to pass.